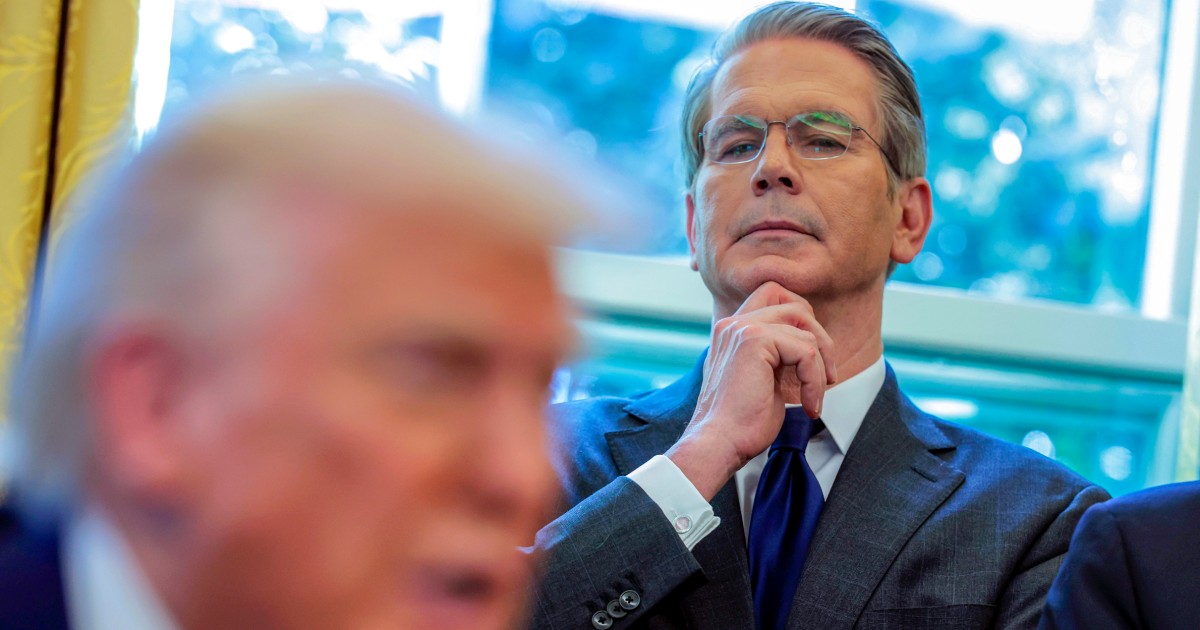
Treasury Secretary Scott Bessent appears to be losing a tug-of-war with the bond markets he is also trying to influence.
asserted
he → appear → markets
In an effort to tamp down on longer-term interest rates and lower the government’s cost of borrowing, Bessent has resorted to an old playbook for tinkering with the bond market and its $30 trillion of U.S. debt backed by the full faith and credit of the United States.
asserted
Bessent → tamp → States
But rather than fall in line, bond traders have taken the opposite side of the Trump administration’s trade, extending a sell-off of U.S. Treasurys and pushing interest rates to multiyear highs.
asserted
traders → fall → highs
Now, the Trump administration may be running out of moves.
uncertain
administration → run → moves
It all began last month, when Bessent made a surprise move and promised to “at least double” the government’s typical repurchases of government debt.
asserted
Bessent → begin → debt
The administration hoped the announcement would stir more demand for bonds and lower market pricing on interest rates.
asserted
announcement → hop → rates
That, in theory, would have reduced the cost for the U.S. government to pay its bills, as the nation’s debt crossed the $40 trillion mark.
asserted
debt → reduce → mark
In tandem with moves to stop the Japanese yen’s depreciation against the U.S. dollar, the messaging from the Treasury Department was clear: It wanted to stop the sell-off in U.S. Treasurys.
asserted
It → stop → Treasurys
Bessent’s message to the market was clear, too: Don’t bet against me.
asserted
message → bet → me
“I have asymmetric information.
asserted
I → have → information
I am the house now,” Bessent said at an event in Texas on Sept. 8.
asserted
Bessent → say → Sept.
“You can bet against me if you want.”
asserted
you → bet → me
A day later, the Treasury Department announced $6 billion in repurchases of longer-dated 10- to 20-year government bonds.
asserted
Department → announce → bonds
And right away, the markets appeared keen to bet against Bessent.
asserted
markets → appear → Bessent
Following the announcement, 10-year yields rose to as high as 4.85%.
asserted
yields → follow → %
Those yields continued surging to 4.95% by the end of Thursday, the highest rate since November 2023 and a roughly 0.30-point jump since Bessent began the repurchase announcements in August.
asserted
Bessent → surge → August
The size of the bond buybacks are “at this point, not enough to make a difference” on interest rates, said bond strategist Guy LeBas.
asserted
LeBas → make → rates
To wit, on the same day the U.S. Treasury offered to buy back $6 billion in longer-dated bonds, it also issued $39 billion in 10-year notes alone.
asserted
it → offer → notes
Asked for his opinion of the Trump administration’s strategy, LeBas pointed to his computer.
asserted
LeBas → ask → computer
“An awful lot of red on my screen gives a better opinion of the strategy,” he said.
asserted
he → give → strategy
Bessent left the door open to further increases in buybacks.
asserted
Bessent → leave → buybacks
But first with the yen intervention and now with buybacks failing to depress longer-term rates, the Treasury Department may be running out of tools — short of more drastic moves like discontinuing some longer-dated bond issuance entirely.
uncertain
Department → fail → issuance
Wall Street analysts have also noted that Bessent’s moves are unusual.
asserted
moves → note → ?
“Treasury debt management is entering a new regime,” the Bank of America research team wrote in a recent note to clients.
asserted
team → enter → clients
They described Bessent’s intervention as “activist,” noting that the Treasury Department was interfering in a way that had not been seen since World War II.
asserted
that → describe → II
In 1942, the Federal Reserve agreed to work with the Treasury Department to broadly peg interest rates lower in order to facilitate large wartime deficits.
asserted
Reserve → agree → deficits
There’s also thinking among Wall Street analysts that the Treasury Department’s failure to convince traders to buy up bonds (and thus to lower rates) was the result of a “Streisand effect.”
asserted
failure → ’ → effect
Rather than reassuring markets, the government’s extraordinary attempts to push yields down may have only served to reveal the administration’s fear that it won’t be able to wrangle rates.
uncertain
it → reassure → rates
This may be in part what’s incentivizing traders to continue betting against Bessent.
“Once markets believe Treasury is defending a price, every rise in yields becomes a test of official resolve, and the operations must grow to survive the tests,” billionaire investor Stanley Druckenmiller wrote in a Wall Street Journal op-ed.
uncertain
Druckenmiller → incentivize → ed
More broadly, the run-ups in bond yields reflect economic conditions and expectations for the Federal Reserve.
asserted
ups → reflect → Reserve
Yields had been on the rise since the U.S. went to war with Iran, which lifted oil prices and reignited concerns that inflation would force the Federal Reserve to raise rates.
asserted
inflation → go → rates
The Fed, under Trump-appointed chair Kevin Warsh, meets Tuesday and Wednesday, and it may choose to raise interest rates for the first time since 2023.
uncertain
it → appoint → 2023
But while the Fed targets shorter-term interest rates, yields on longer-dated U.S. Treasurys (like 10-year and 30-year rates) are more market-driven.
asserted
yields → target → rates
This means that traders speculating on future economic conditions have a substantial say in determining the government’s longer-term borrowing costs.
asserted
traders → mean → costs
They also influence the rates consumers pay, because credit card rates, mortgage rates and other household-facing borrowing costs are benchmarked against longer-dated U.S. Treasury yields.
asserted
rates → influence → yields
Unlike stock in a company, a buyer of U.S. Treasurys lends the government money on the promise that it will be repaid, in full and with interest, over a period of time (i.e., one month, or as long as 30 years).
asserted
it → lend → years
The interest paid on those securities is called the “yield.”
asserted
interest → pay → securities
In secondary markets, where traders buy and sell U.S. Treasurys from one another, yields fluctuate based on demand and supply.
asserted
yields → buy → demand
When the price of a bond falls due to low demand (or a glut of supply), yields generally rise.
asserted
yields → fall → supply
When the price of a bond rises due to high demand (or short supply), yields generally fall.
asserted
yields → rise → demand
…and 2 more, not listed.